If you buy a home in Canada with less than 20% down, you will pay for CMHC insurance. It is one of the biggest costs first-time buyers overlook, because it rarely comes out of your pocket at closing. Instead, the premium is usually added to your mortgage, so you pay interest on it for years.
So this guide explains what CMHC insurance is, the 2026 premium chart, real cost examples and four legal ways to reduce or avoid it.
What is CMHC insurance?
First, CMHC insurance, also called mortgage default insurance, protects your lender, not you. So if you stop paying, the insurer covers the lender’s loss. As a result, lenders can offer high-ratio mortgages with as little as 5% down, and often at their lowest rates.
Although people call it “CMHC insurance”, there are three insurers in Canada: the Canada Mortgage and Housing Corporation (CMHC), Sagen and Canada Guaranty. Their premiums are generally very similar, and your lender chooses the insurer.
Insured vs. uninsured mortgages
Insured (under 20% down)
- CMHC insurance premium required
- Home price must be under $1.5 million
- Often the lowest interest rates
- 30-year amortization only for first-time buyers and new builds
Uninsured (20%+ down)
- No insurance premium
- No price cap
- Rates can be slightly higher
- 30-year amortization widely available
Mortgage default insurance premium chart (2026)
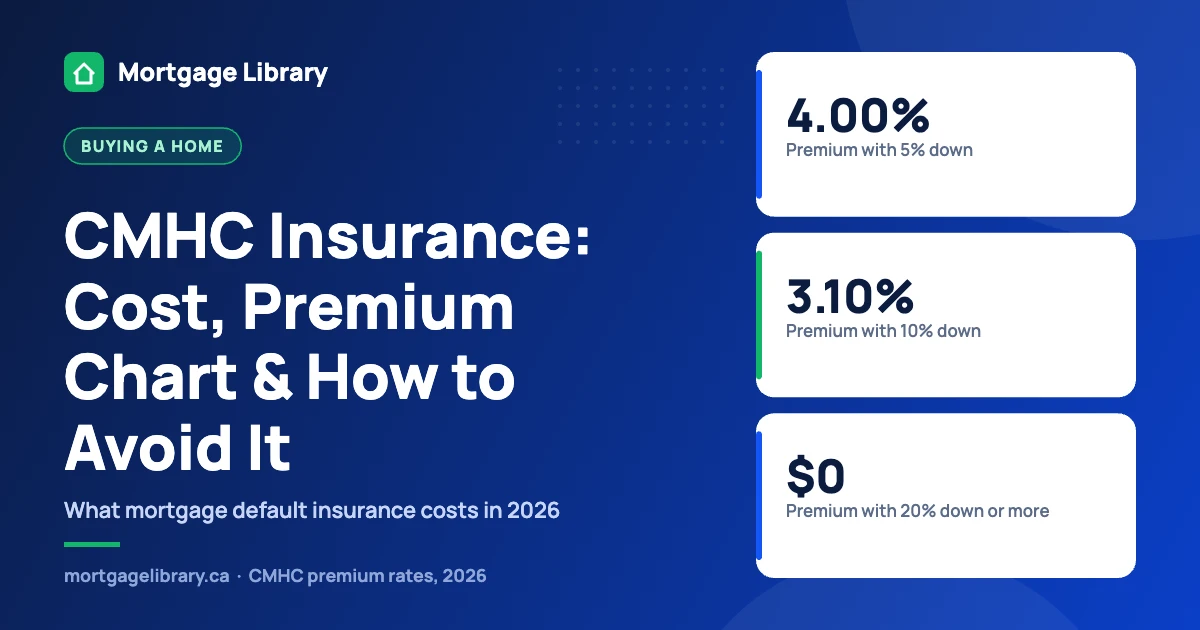
Your premium depends on your loan-to-value ratio, which is your mortgage divided by the home price. So the smaller your down payment, the higher the rate. Here, then, are the current CMHC premium rates:
CMHC insurance premiums by down payment
| Down payment | Loan-to-value | Premium (% of mortgage) |
|---|---|---|
| 5% to 9.99% | 90.01% to 95% | 4.00% |
| 10% to 14.99% | 85.01% to 90% | 3.10% |
| 15% to 19.99% | 80.01% to 85% | 2.80% |
| 20% or more | 80% or less | Not required* |
How much does CMHC insurance cost? Real examples
To see the real cost, multiply your mortgage amount by the premium rate. For example, on a $500,000 home:
Insurance premium on a $500,000 home
So how much is mortgage insurance on a $500,000 loan? At 95% loan-to-value, it is 4.00%, or $20,000. At 90% loan-to-value, however, it drops to 3.10%, or $15,500. In other words, a bigger down payment saves you twice: you borrow less, and you also pay a lower premium rate.
Don’t forget the sales tax on the premium
In Ontario and Quebec, provincial sales tax applies to the premium. Unlike the premium, however, this tax cannot be added to your mortgage, so you pay it at closing. For example, with 5% down on a $500,000 home in Ontario, the 8% tax adds about $1,520 to your closing costs.
How to avoid CMHC insurance (or pay less)
Ultimately, the only way to avoid CMHC insurance entirely is to put down at least 20%. Still, there are several ways to get there, or to shrink the premium when you can’t.
- Reach 20% down. Combine savings with tax-free accounts such as the FHSA and the RRSP Home Buyers’ Plan.
- Use a gifted down payment. Most lenders also accept a gift from an immediate family member with a signed gift letter.
- Cross a premium tier. For example, moving from 9% down to 10% cuts the premium rate from 4.00% to 3.10%. So on a $500,000 home, that one extra percent saves about $4,500.
- Buy a less expensive home. A lower price also reduces both the down payment you need and the premium.
Also, check whether your purchase qualifies for a partial premium refund. For instance, CMHC has offered refunds through its Eco Plus program for energy-efficient homes, so ask your lender or broker.
Is CMHC insurance worth it?
For many buyers, yes. Saving a full 20% can take years, especially in high-cost cities, while home prices and rents keep moving. In addition, insured mortgages often get the lowest rates, which partly offsets the premium.
However, the premium is a real cost. So compare the premium against what you would pay in rent while you save the extra down payment. For a full breakdown of minimums, read our minimum down payment guide, and then check how much mortgage you can afford.
Frequently asked questions
CMHC insurance costs 2.80% to 4.00% of your mortgage, depending on your down payment. With 5% down, the premium is 4.00%, while with 15% down it falls to 2.80%. Also, a 30-year amortization adds 0.20%.
Put down at least 20% of the purchase price. Tax-free accounts such as the FHSA, the RRSP Home Buyers’ Plan and gifts from family can also help you reach that amount.
Usually not. Instead, the premium is normally added to your mortgage balance and paid off over your amortization. However, provincial sales tax on the premium in Ontario and Quebec must be paid at closing.
At 95% loan-to-value, the premium is 4.00%, or $20,000. At 90% loan-to-value, however, it is 3.10%, or $15,500.
Sources: CMHC premium information · CMHC: Qualifying for mortgage insurance · CMHC premium changes (2024)